Thailand's real estate growth shifts beyond Bangkok
Thu, 22nd Oct 2026 (Today)
JLL has identified Thailand as well placed to benefit from structural shifts in Southeast Asia's real estate market, with growth extending beyond Bangkok into industrial and tourism-linked regions.
Thailand's Eastern Economic Corridor remains the main anchor of expansion, but investment activity is also spreading to second-tier cities and coastal destinations. JLL also pointed to a broader regional pattern in which infrastructure investment, supply chain diversification, digitalisation and tighter sustainability standards are reshaping where capital is directed.
Thailand's changing real estate map reflects a shift away from a model concentrated on the capital. Growth is becoming more distributed, with the Eastern Seaboard, industrial townships and tourism-focused areas taking a larger share of development.
Part of that shift is tied to industrial policy and manufacturing trends. Thailand is moving further into higher-value industrial segments such as electronics, electric vehicles, specialised manufacturing and advanced logistics, as companies adjust supply chains under so-called China+1 strategies.
This is changing the nature of industrial property demand. Managed industrial parks and sector-specific clusters are gaining importance over more traditional land banking and warehouse-led approaches, particularly in areas linked to the Eastern Economic Corridor and the U-Tapao aviation hub.
Industrial focus
The findings place Thailand alongside other Southeast Asian markets where governments are using policy and infrastructure to shape investment patterns. Across the region, transport links, special economic zones and other state-led initiatives are widening the range of locations considered investable beyond traditional central business districts.
In Thailand, this has created what JLL describes as a more networked pattern of growth. The report identifies the Eastern Economic Corridor as one of several connected regional growth systems in Southeast Asia, alongside the Johor-Singapore axis, Northern Luzon and Vietnam's large regional clusters.
Industrial and logistics assets are one of four cross-cutting themes identified for investors and occupiers in Thailand. The others are data centres and digital infrastructure, asset repositioning and conversion, and cross-border corridor opportunities.
Bangkok remains central to the office and retail story, but the focus there is different. Rather than new development alone, ageing stock in the capital offers scope for retrofit, conversion and repositioning as occupiers place greater weight on building quality and environmental standards.
Rising ESG expectations are widening the gap between modern assets and outdated buildings. That is contributing to a broader "brown discount" for properties that are poorly configured, energy-inefficient or functionally obsolete.
Tourism markets
Outside the capital, JLL highlighted opportunities in hospitality, retail and residential projects linked to tourism and wellness. Phuket was described as an established global resort destination, while Phang Nga was identified as an emerging coastal market.
Wellness-led development is expected to play a bigger role in tourist-driven locations, especially across retail, ultra-luxury residential and hospitality segments. The report also noted that larger developers in Thailand are shifting towards recurring-income assets, contributing to a more diversified development pipeline.
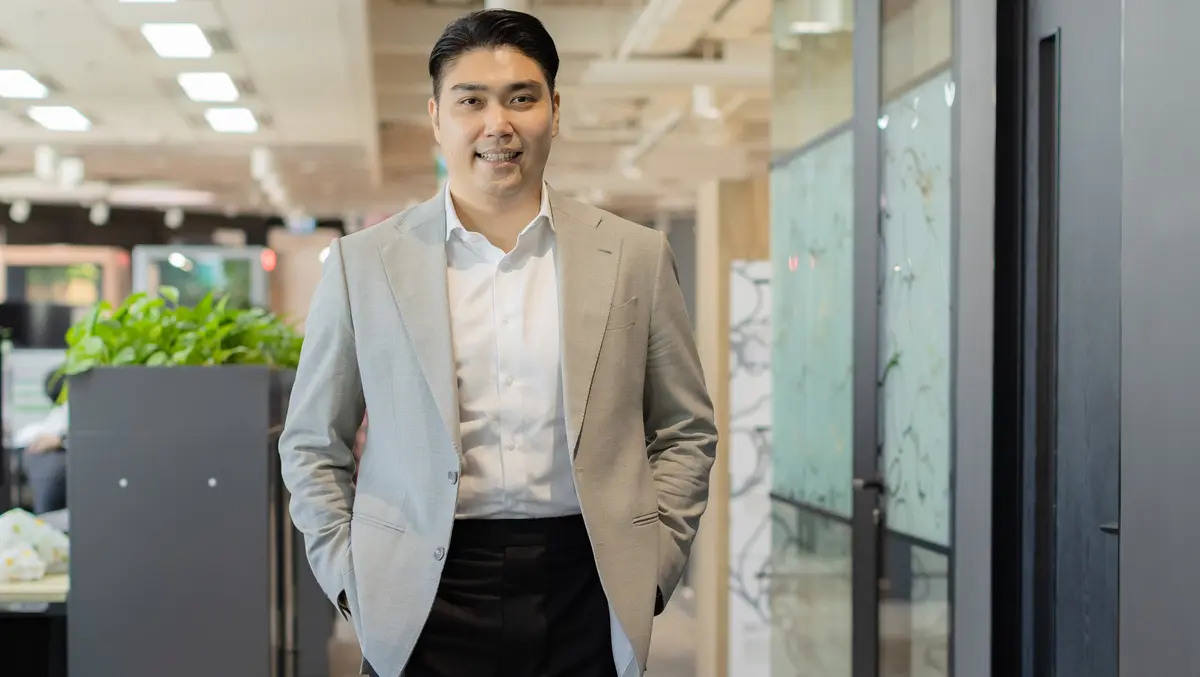
Krit Pimhataivoot, Country Head & Head of Capital Markets, JLL Thailand, said the market was becoming more selective as investors and occupiers focused more tightly on fundamentals.
"Thailand's real estate market is moving into a more selective phase, where success depends on focusing on strong fundamentals. While policy and infrastructure remain key drivers, capital is deploying into highly specialised areas. We see this in the sustained demand for advanced industrial estates, the robust expansion of world-class tourism, hotel, and wellness developments in premier coastal destinations, and, in Bangkok, the practical opportunity of converting and upgrading existing office buildings to meet modern demands," said Pimhataivoot.
Regional shift
The wider Southeast Asian context is a key part of the assessment. JLL argues the region's outlook should be viewed less through a cyclical recovery lens and more through structural forces reshaping geography, asset selection and sector priorities.
That means broad exposure to a country or region may matter less than specific positions within growth corridors, sectors and asset types. In Thailand, the report suggests the strongest interest is likely to cluster around advanced industrial estates, tourism-linked destinations and urban assets that can be upgraded for new uses.
Dr Yang Liang Chua, Head of Research & Advisory, Southeast Asia, JLL, said Thailand reflects a wider regional shift towards more distributed growth.
"Thailand is a prime example of the regional expansion occurring across Southeast Asia, shifting from a Bangkok-focused market to a highly diversified, multipolar landscape. Investors are capitalizing on specialized opportunities across different regions, from advanced industrial estates in the Eastern Economic Corridor to premier, self-sustaining luxury hospitality and wellness markets in Phuket and upcoming coastal locations like Phang Nga," said Chua.
He added that Thailand should be viewed within a broader regional framework rather than as a single-city market.
"For investors and occupiers alike, Thailand offers compelling upside, particularly for those who approach it as part of a connected, multipolar system," he said.